How Many Car Payments Can You Miss Before Repo? The Ultimate Guide
When you miss a car payment, it’s natural to worry about the possibility of repossession. So, how many car payments can you miss before repo becomes a real threat? Understanding this process and knowing your options can help you navigate these challenging circumstances.
How Auto Loans Work
An auto loan allows you to finance a vehicle and pay it off over time in monthly installments. When you sign the loan agreement, you agree to terms including interest rates, repayment schedules, and consequences for missed payments. If you miss payments, the lender can take back or repossess the vehicle to recoup their losses.
What Is Repossession?
Repossession occurs when a lender takes back property—such as a car—due to missed loan payments. Since auto loans are typically secured loans, the vehicle is collateral. If you fail to make payments as agreed, the lender can reclaim and sell the car to offset the remaining loan balance.
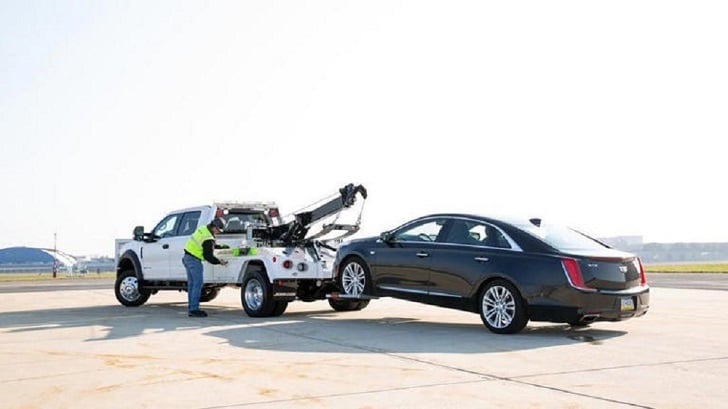
Quartz | MSN | Repossession occurs when a lender takes back car—due to missed loan payments.
How Many Car Payments Can You Miss Before Repo?
The specific number of car payments you can miss before your car is repossessed varies by lender. Some lenders might allow three or more missed payments, while others may initiate repossession after just one missed payment. It’s important to understand your loan agreement and communicate with your lender if you anticipate trouble making a payment.
Risk of Repossession After One Missed Payment
In many cases, you could face repossession after missing just one payment. This depends largely on your lender’s policies. Even if your lender is more lenient, missing a payment can have severe consequences, such as damaging your credit score. If you miss a car loan payment, it typically shows up on your credit report and can stay there for up to seven years, impacting your ability to secure future loans.
Impact of Late Payments on Credit Score
Lenders often report late car payments to credit bureaus, which can lower your credit score immediately. A single late payment might not be as damaging as a missed payment, but it can still affect your credit, especially if it’s overdue by 30 days or more. The longer a payment goes unpaid, the greater the negative impact. If you know you’ll be late, it’s crucial to contact your lender and arrange payment as soon as possible.
Does Your Lender Have to Notify You Before Repossession?
Lenders do not have to notify you before repossessing your car unless it is stipulated in your loan agreement. This lack of notice can catch many borrowers off guard, making it essential to stay current on payments and maintain open communication with your lender.
What to Do If You Miss a Car Payment
If you miss a car payment, take immediate action to mitigate the consequences. Here are a few steps you can take:
Contact Your Lender
The first step is to contact your lender. If you have a missed payment but can afford to pay it, request that they reprocess the payment. For those with automatic payments, a technical issue may have caused the missed payment. If you cannot afford to pay, discuss the possibility of extending the due date or waiving late fees. Many lenders are willing to work with borrowers experiencing temporary financial hardships.
Examine Your Options
If you’re unable to make a payment, consider requesting a loan deferment. This allows you to temporarily pause payments, giving you time to gather funds. If your financial issues are ongoing, explore other options, such as loan modification, which can adjust your loan terms, interest rate, or even the loan type.
Adjust Your Budget
Evaluate your financial situation and adjust your budget to prioritize your car payment. Cutting unnecessary expenses can free up funds to ensure you stay current on your loan. If inflation or other financial pressures make this difficult, consider seeking financial counseling for additional strategies.
EVG Kowalievska | Pexels | Evaluate your financial situation and adjust your budget to prioritize your car payment.
How to Get a Repossessed Car Back
If your car is repossessed, it’s not necessarily the end. There are ways to get your vehicle back and even improve your credit score in the process.
Reinstate the Loan
You can reinstate your loan by making a lump-sum payment that covers the overdue amount, including any late fees and repossession costs. Negotiating with your lender might allow you to reach a more manageable repayment plan.
Pay Off the Car
Another option to reclaim your vehicle is to pay off the entire loan balance along with any associated fees. While costly, this method ensures you won’t have to make future payments.
Buy the Car at Auction
If the car goes to auction, you have the option to bid on it. The lender will notify you of the auction details, allowing you to potentially buy back your car. This option might leave you with an outstanding loan balance, but it can get the car back in your possession.
More inCar Insurance
-
 Credit Acceptance Pays $710 Million to Settle Predatory Auto Lending Claims
One of America’s largest subprime auto lenders has agreed to a massive settlement over allegations that it put financially vulnerable...
October 1, 2026 -
 EV vs. Hybrid vs. Gas | Which Car Works Best for a Road Trip?
A long road trip can reveal differences that city driving often hides. Charging time, fuel stops, highway range, energy prices,...
September 27, 2026 -
 Diesel Prices Exceed Historic $6 a Gallon as Iran War Intensifies
Diesel prices are soaring in the U.S. The national average reached $6.2694 per gallon on September 15, 2026, according to...
September 25, 2026 -
 Adding Your Teen to Your Car Insurance? Costs and Ways to Save
A newly licensed teen can bring excitement to a household, but the first auto insurance bill may bring a surprise....
September 19, 2026 -
 Here’s How Much Spending Money Your College Student Should Get
The tuition is paid, the dorm room is booked, the meal plan is set, and the car is packed. Your...
September 18, 2026 -
 How Much Money Should You Keep in an Emergency Fund?
With everyday expenses remaining high across the U.S. in 2026, an emergency fund can provide a needed buffer when an...
September 13, 2026 -
 How Staying With the Same Car Costs You More in Insurance
Loyalty usually sounds like something a company should reward. Stay with the same business for years, pay your bills on...
September 11, 2026 -
 State Farm Is Sending Out $5 Billion in Dividends. Here’s Who Qualifies
After several years of rising auto insurance costs, some State Farm customers are now getting money back. State Farm has...
September 6, 2026 -
 Nissan’s Big Bet on Aggressive Discounts Is Fueling Sales As Competitors Pull Back
Nissan is spending more money to get buyers into its cars, and the strategy is producing results. While several major...
September 3, 2026 -
 Hyundai Gives Its Wild Baja Santa Fe Render the Green Light
The Hyundai Santa Fe is designed as a practical family SUV, but a new digital rendering gives it a very...
August 30, 2026 -
 Andy Green and JCB Set New Hydrogen Speed Record of 406 MPH
Hydrogen power just had a very fast day in Utah. British land speed legend Andy Green drove the JCB Hydromax...
August 27, 2026 -
 Ford Reveals “Fathom,” Its New Electric Truck With a $29,945 Price Tag
Ford is preparing a new electric pickup called the “Fathom,” with a planned starting price of $29,945 after destination. The...
August 22, 2026 -
 The Median Net Worth for Americans at Age 40 is Roughly $135k, Survey Shows
Turning 40 can make money feel more serious. Retirement no longer seems impossibly far away, housing costs may be substantial,...
August 20, 2026 -
 Michigan Woman Loses $1,000 in Ghost Tapping Payment Scam
Contactless payments have made shopping faster than ever, but scammers are finding new ways to misuse the same technology. A...
August 15, 2026
You must be logged in to post a comment Login